The $27 Trillion Time Bomb: Why the Treasury Market Is Even Shakier Than It Looks
The U. S.
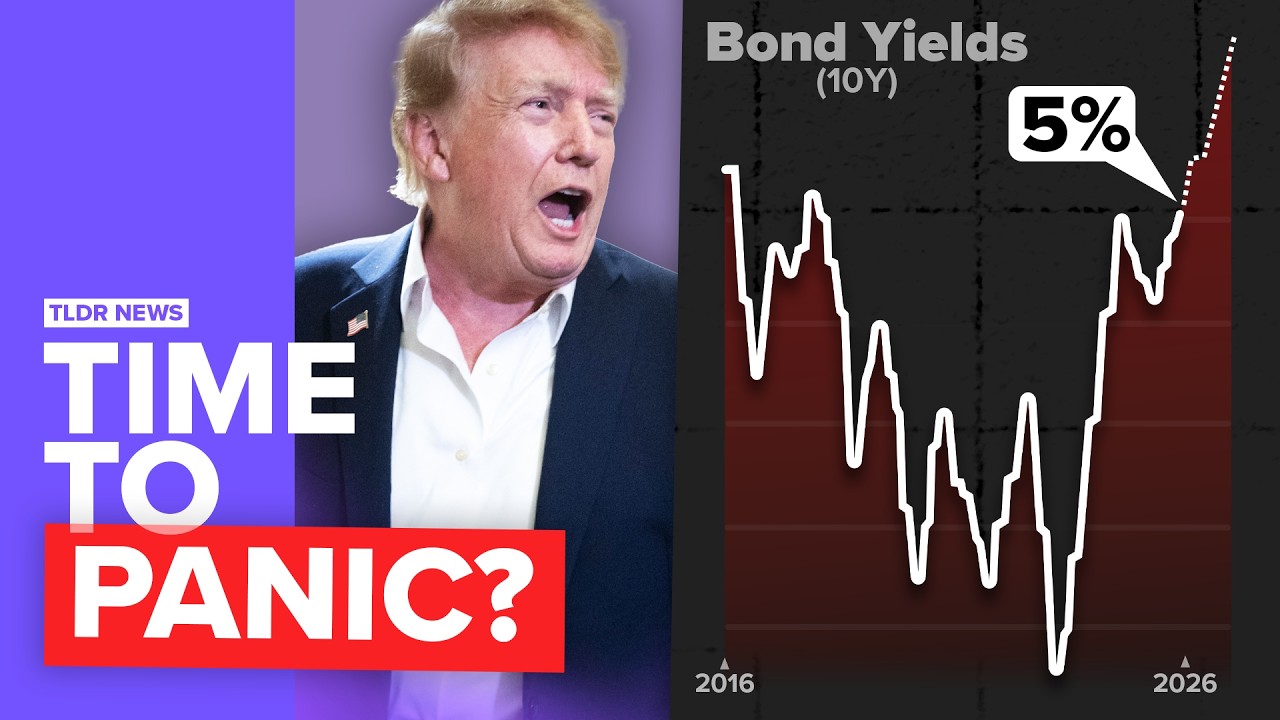
The U.S. Treasury market is the bedrock of the global financial system. It sets the "risk-free" rate against which every asset on Earth is priced, and it serves as the ultimate safe haven in times of crisis. But beneath the surface of this $27 trillion market, structural fractures are widening. The market is becoming more fragile, less liquid, and increasingly vulnerable to shocks—a reality that contradicts its reputation for stability.
The Illusion of Liquidity
On paper, the Treasury market looks robust. Daily trading volumes exceed $700 billion. However, volume does not equal liquidity. Liquidity refers to the ability to buy or sell an asset quickly without causing a significant change in its price.
In reality, the market's depth—the ability to absorb large trades—has deteriorated. When volatility spikes, buyers vanish. This was evident during the "Flash Rally" in 2014 and the "Dash for Cash" in March 2020. In both instances, the world's deepest market froze, requiring central bank intervention to function.
The Leverage Problem
A primary driver of this fragility is the explosion of hedge fund leverage. Through the "basis trade," hedge funds exploit tiny price differences between Treasury futures and cash bonds. To make these razor-thin margins profitable, they borrow heavily—often at ratios of 50-to-1 or more.
This strategy creates hidden risks. Because these positions are highly leveraged, a small drop in prices can trigger margin calls. If funds are forced to sell their holdings to meet these calls, they can spark a cascade of selling. This "crowded trade" has grown so large that it now poses a systemic risk to the entire financial system.
The Buyer Base Has Shifted
The identity of the marginal buyer has changed. Historically, price-insensitive buyers—like central banks and commercial banks—absorbed supply regardless of yield. Today, that demand has waned. Central banks are diversifying reserves, and banks are constrained by post-2008 regulations.
Instead, the market now relies on price-sensitive buyers: hedge funds and mutual funds. These participants are quick to exit when conditions worsen. This shift means that when the government issues new debt to fund its deficit, it must offer higher yields to attract buyers. This dynamic puts upward pressure on interest rates and increases borrowing costs for the entire economy.
The Regulatory Blind Spot
Regulators face a difficult challenge. Much of the trading activity has moved to the shadows of the market—specifically, the Treasury repo market. Repurchase agreements (repos) are short-term loans collateralized by Treasuries. While crucial for market functioning, this market is opaque.
The Financial Stability Oversight Council (FSOC) has flagged the Treasury market as a potential vulnerability. However, implementing reforms is difficult. Stricter capital rules might prevent banks from acting as intermediaries during crises, while looser rules could encourage excessive risk-taking. The market is caught in a regulatory limbo.
The Implications
Why does this matter to the average investor? The Treasury market is the plumbing of the financial system. If the plumbing backs up, the entire house floods.
A dysfunctional Treasury market would:
- Impair Monetary Policy: The Federal Reserve uses Treasuries to conduct open market operations. If the market is broken, the Fed loses its primary tool for controlling interest rates.
- Raise Borrowing Costs: A lack of liquidity leads to higher yields. This translates to higher mortgage rates, auto loans, and corporate borrowing costs.
- Trigger Contagion: Because Treasuries are used as collateral worldwide, a sudden drop in their value could trigger margin calls across the globe, similar to the 2008 financial crisis.
Conclusion
The Treasury market is no longer the risk-free, infinitely liquid monolith it once was. It is a market stretched by massive debt issuance, reliant on leveraged players, and vulnerable to sudden stops. While a total collapse is unlikely, the "shakiness" is real. Investors and policymakers must recognize that the foundation of the global financial system requires urgent structural repair.
Related Coverage
Hedge Funds Now Run the $27 Trillion Treasury Market — And That’s a Problem
Wall Street’s safest corner has become its riskiest bet: hedge funds now dominate the $27 trillion U.S. Treasury market, using heavy borrowing to chase tiny price differences, a strategy that could trigger a sudden sell-off and spike government borrowing costs if one major fund fails.
Trump Admin’s Bond Market Meddling Could Blow Up Your Mortgage Rates
The Trump administration is pushing for more control over how U.S. government bonds are issued and priced, a move that experts warn could raise borrowing costs for everyday Americans instead of lowering them.
War, Debt, and an AI Gamble: How the Global Economy Buckled in 2026
A year of failed ceasefires, record borrowing costs, and a trillion-dollar artificial intelligence bet has exposed a global economic order that rewards financial accumulation while leaving ordinary people to absorb the shocks.
War, Debt, and an AI Gamble: How the Global Economy Buckled in 2026
A year of failed ceasefires, record borrowing costs, and a trillion-dollar artificial intelligence bet has exposed a global economic order that rewards financial accumulation while leaving ordinary people to absorb the shocks.
Wars, Debt, and an AI Reckoning: The Forces Reshaping Nations in 2026
A year of converging crises—from Gaza and Ukraine to a global debt squeeze and runaway AI—is testing governments and exposing who pays the price.
War, Debt, and an AI Gamble: How the Global Economy Buckled in 2026
A year of failed ceasefires, record borrowing costs, and a trillion-dollar artificial intelligence bet exposed a global economic order that rewards financial accumulation while leaving ordinary people to absorb the shocks.
Related Editorials
Britain's Debt Time Bomb: Why the Budget's Blind Spot Could Sink the Economy
Introduction Britain's national debt has quietly become a crisis hiding in plain sight. While successive budgets have focused on headline spending figures and short-term giveaways, a far more dangerous problem has been building: the true scale of the country's liabilities is far larger than off
The $3.5 Trillion Shadow: Why the Global Debt Time Bomb Is Still Ticking
A financial crisis is unfolding in plain sight, yet it remains largely absent from mainstream headlines. It is not a bank run, a stock market crash, or a sudden currency devaluation.
America’s Debt Bomb: Is the Fiscal Reckoning Finally Here?
The United States has long operated on a fiscal knife’s edge, borrowing trillions to fund its ambitions. For decades, economists have warned that the bill would come due, only to see the day of reckoning perpetually postponed.
The Next Financial Crash: Why “Uninvestable” Assets Are the Real Threat
The global financial system is a complex web of interdependencies. When a major shock occurs—like a pandemic or a sudden spike in interest rates—the initial damage is often visible.
Britain’s £100 Billion Question: Where Can the Money Come From?
Introduction Britain faces a daunting fiscal challenge: finding £100 billion a year to rebuild its economy. The scale of the problem is enormous, but the solutions are more varied—and more controversial—than they might first appear.
Britain's Debt Machine: How the Bond Market Moves Wealth from the Poor to the Rich
The UK's national debt stands at roughly 100% of GDP. The interest bill alone exceeds the defence budget.